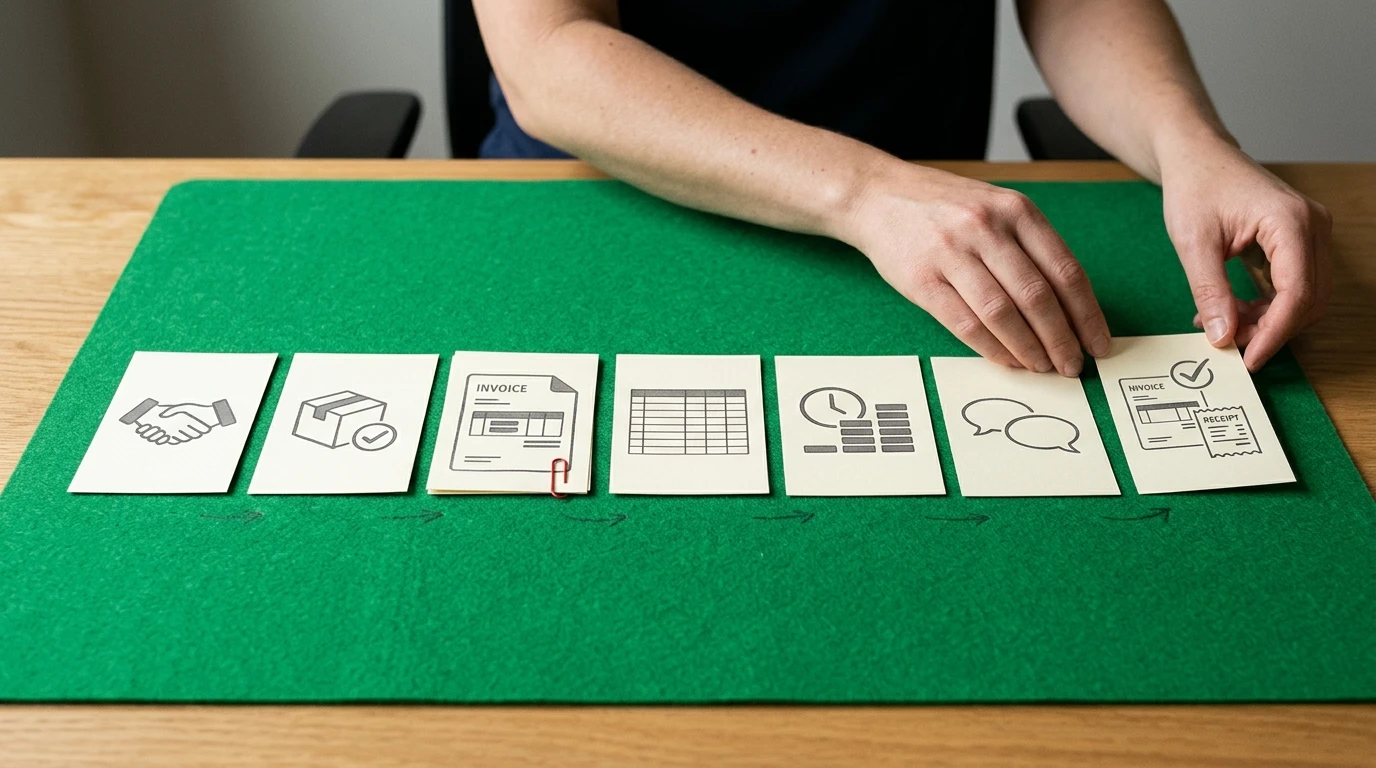
Chasing unpaid invoices takes time away from paid work. Your accounts receivable process is the workflow that moves a credit sale from agreed payment terms to collected, reconciled cash. An invoice records money owed, not money received. Build the workflow around clear ownership, accurate billing, and a next action for every unpaid balance.
Build Your Accounts Receivable Process in Seven Steps
A workable receivables process connects sales, billing, collections, and bookkeeping. J.P. Morgan’s accounts receivable management guidance describes the same underlying purpose: managing money customers owe so sales turn into available cash.
For a freelancer, one person may handle every step. An agency may divide them between an account manager and a bookkeeper. Assign an owner to each handoff, even when the same name appears throughout.
-
Agree on credit terms before accepting the work.
Decide whether the customer pays upfront, by milestone, or after delivery. Before extending credit, check the customer’s payment history where available and set an exposure limit you can afford.
Confirm the legal customer name, billing contact, payment terms, and any purchase order or supplier-portal requirements. A project manager’s approval will not necessarily get an invoice through the customer’s accounts payable team.
-
Keep evidence that the work was delivered.
Save the signed agreement and evidence of completion, such as written milestone approval or a delivery receipt. For ongoing services, record the billing period and agreed scope.
This gives you something specific to resolve if the customer later disputes the charge. “Website milestone approved on April 1” is more useful than “project completed.”
-
Create and deliver an invoice the customer can process.
Include a unique invoice number, your business details, the customer’s correct billing entity, an itemized description, applicable taxes, currency, amount due, and an explicit due date. Add the purchase order reference when required and clear payment instructions.
Send it through the agreed channel. If the customer requires a portal upload, an email attachment alone may leave the invoice outside their approval queue. Record delivery or submission confirmation.
-
Record the receivable in your accounting system.
Connect invoicing and accounts receivable by keeping one authoritative invoice record. Track its original amount, due date, credits, payments, and outstanding balance.
Under accrual accounting, when an earned service sale is recognized on credit, the usual entry debits accounts receivable and credits revenue, with applicable taxes recorded separately. Avoid creating another sales entry when importing an invoice already recorded by a connected system.
-
Review open balances and assign the next action.
Use an aging report to group unpaid balances by how long they have been overdue. Check whether your report ages invoices from the due date or invoice date, because those views answer different questions.
Review overdue balances alongside disputes and promised payment dates. An invoice awaiting a corrected purchase order needs a different action from one whose customer promised payment tomorrow.
-
Follow up and resolve the reason payment has stalled.
Send reminders that identify the invoice, remaining balance, and due date. Ask for a specific payment date when the invoice is overdue, rather than another vague confirmation that it is “being processed.”
Record the reply and change the next action accordingly. A dispute goes to someone who can resolve it. A promise to pay gets a dated checkpoint. Silence triggers your agreed escalation route.
-
Apply the payment and reconcile the records.
Match the receipt to the correct customer and invoice using the payment reference or remittance advice. Under accrual accounting, the usual payment entry debits cash and credits accounts receivable.
Apply partial receipts without closing the remaining balance. Reconcile customer balances to the receivables control account and payment records to the bank, accounting separately for processing fees. Investigate unmatched receipts instead of marking invoices paid by guesswork.
Choose tools after defining these handoffs. The small-business accounts receivable software guide covers the broader software decision when your workflow needs more than a shared tracker.
Make Follow-Ups Respond to What the Customer Says
A customer reply should change the collection action. Sending the same reminder after someone reports a billing error makes the process feel careless and leaves the actual obstacle untouched.
Use the following routing table as an operating policy. Set reminder timing around your agreed terms and customer relationships rather than treating one schedule as universal.
| Invoice situation | Next action | What to record |
|---|---|---|
| Due date approaching | Confirm receipt and check for approval blockers | Delivery confirmation and billing contact |
| Overdue with no reply | Request payment or a specific payment date | Last contact and next follow-up date |
| Customer promises payment | Confirm the amount and date, then check for receipt | Promise amount, date, and status |
| Promise date passes without receipt | Check payment records, then request an updated commitment | Missed promise and escalation owner |
| Customer disputes the charge | Route the issue to the person who can resolve it and pause routine reminders on the disputed amount | Disputed amount, reason, and resolution deadline |
| Customer makes a partial payment | Apply the receipt and confirm the remaining balance | Amount received and next payment date |
| Customer says payment was sent | Request remittance details and investigate | Payment reference, date, and matching status |
Repeated “just following up” emails rarely clarify what is wrong. Ask a question the recipient can answer: whether the invoice is approved, what is blocking payment, or when the outstanding amount will be paid.
For wording, adapt these overdue invoice reminder email templates to the invoice’s actual status. Keep sensitive disputes with a named person, and set boundaries on contact channels, frequency, and escalation.
Late fees, service suspension, and external collection action need separate approval. Check the contract and applicable law before taking those steps.
Work Through an Invoice, Then Copy the Tracking Template
Say your agency issues a $3,000 invoice on April 1, with payment due May 1. The customer pays $1,000 on April 25, then promises the remaining $2,000 for May 9 after you follow up on May 2.
The invoice stays open until the remaining payment arrives and is matched. The promise changes the follow-up date, but it does not reduce the receivable.
| Event | Accounting or workflow action | Remaining receivable |
|---|---|---|
| April 1: earned service invoiced | Record the invoice and May 1 due date | $3,000 |
| April 25: partial payment received | Apply $1,000 to the original invoice | $2,000 |
| May 2: customer promises May 9 payment | Record the promise and schedule a receipt check | $2,000 |
| May 9: remaining payment received and matched | Apply $2,000 and close the invoice | $0 |
Never change the contractual due date just to store a payment promise. Keeping both dates preserves the overdue history while letting you follow the customer’s commitment.
Copy this record into your existing tracker or use it to assess whether your accounts receivable templates capture enough detail:
Customer legal name:
Invoice number:
Invoice date:
Contractual due date:
Currency:
Original invoice amount:
Credits applied:
Payments applied:
Outstanding balance:

Billing contact:
Invoice delivery method:
Delivery or portal confirmation:
Purchase order reference:
Delivery or acceptance evidence:

Collection status:
Disputed amount and reason:
Last contact date:
Customer response:
Promised payment amount:
Promised payment date:
Next action:
Next action date:
Action owner:
Escalation approval required:

Payment reference:
Payment matched date:
Reconciliation status:
Keep accounting status and collection status separate. An invoice can be partly paid and disputed at the same time, so one “pending” label will hide useful information.
Check Whether the Process Is Working
A healthy receivables workflow makes stalled invoices visible early and keeps balances accurate. Review open invoices regularly, with particular attention to missing next actions, unresolved disputes, and broken payment promises.
Track the overdue balance and its share of total receivables over time. Count missed promises separately from unanswered reminders, because a customer who repeatedly commits and fails to pay needs a different decision from one whose invoice reached the wrong inbox.
For a broader collection-efficiency measure, use consistent periods and credit-sales data. This explanation of what accounts receivable turnover tells you about collections covers how average accounts receivable fits into that calculation.
We recommend fixing process gaps before adding more reminders. Accounts receivable automation can handle routine follow-up, but a missing purchase order or incorrect invoice still needs resolution.
Frequently Asked Questions
What are the risks of accounts receivable?
The main risks are late payment, nonpayment, billing disputes, and inaccurate records that overstate what customers owe. Large balances concentrated in one customer also leave your cash flow exposed if that customer delays payment.
What is the difference between accounts receivable and accounts payable?
Accounts receivable is money customers owe your business. Accounts payable is money your business owes suppliers, so a customer payment reduces your receivable while a supplier payment reduces your payable.
How do you calculate net accounts receivable?
Net accounts receivable equals gross accounts receivable minus the allowance for doubtful accounts. For example, if gross receivables are $20,000 and the allowance is $1,000, net receivables are $19,000.
Does a cash-basis business need to track unpaid invoices?
Yes, unpaid invoice tracking still helps you collect customer balances even when your tax accounting uses the cash method. The IRS guidance on cash and accrual accounting methods explains that cash-method income is generally reported when received, while accrual-method income is generally reported when earned.
For the agency invoice, the next action is a payment check on May 9, followed by a targeted response if the promise is missed. Apply that same discipline to your open balances. Bump chases overdue invoices through email and WhatsApp, reads replies, and tracks payment promises within your guardrails. Sign up to automate invoice follow-ups when you are ready to put that workflow into practice.